
Consider a hypothetical example. During the annual Open Enrollment period on Healthcare.gov or your state exchange, you project your upcoming annual household earnings at $34,000. Based on that estimate, the marketplace grants you a substantial monthly Advance Premium Tax Credit (APTC) of $520, lowering your monthly silver plan payment from $560 down to an affordable $40. For twelve straight months, your health insurance operates smoothly.
Then, during the tax year, your circumstances change for the better: you pick up profitable freelance contracts, work overtime, secure a mid-year promotion, or receive an unexpected capital gains distribution. When your final Form W-2s and 1099s arrive, your actual income stands at $52,000—substantially higher than your November projection. When you file your federal tax return, the IRS tax software delivers an unpleasant surprise: an unexpected tax liability of thousands of dollars on Schedule 2.
Underestimating income on the health insurance exchange is one of the most common—and expensive—tax compliance mistakes made by independent contractors, gig workers, and small-business owners. The monthly discount you received was not a guaranteed entitlement; it was an advance payment of a tax credit, based on an estimate, that has to be squared up on your tax return. Understanding how the IRS audits these credits through Form 8962, what statutory repayment limits protect you, and how to deploy legal deductions can prevent painful clawbacks.
1. The Mechanical Reality: How the Advance Tax Credit Works
The Affordable Care Act subsidizes health insurance coverage through the Premium Tax Credit (PTC) authorized under Internal Revenue Code Section 36B (26 U.S.C. Section 36B). The term “advance” is the critical operational factor:
- The Forward Estimate: When you apply on the exchange, you estimate your Modified Adjusted Gross Income (MAGI) for the upcoming tax year. The federal government uses this projection to calculate your theoretical financial need.
- Direct Payer Remittance: The Treasury does not send this money to you; it wires the subsidy directly to your private insurance carrier each month on your behalf.
- The Mandatory Year-End Reckoning: Because your real income cannot be verified until the tax year closes, every single dollar paid in advance must be formally reconciled against your actual finalized tax return using IRS Form 8962 (Premium Tax Credit).
If your actual realized income exceeds your initial projection, the IRS recalculates your allowable credit retroactively. Every dollar of subsidy you received above your legal entitlement is classified as an Excess Advance Premium Tax Credit Repayment, which is added directly to your federal income tax balance on IRS Form 1040, Schedule 2.
2. The True Danger: The Audit on IRS Form 8962
In January, your health insurance exchange mails you a formal tax document called Form 1095-A (Health Insurance Marketplace Statement). This document lists three critical figures across twelve monthly columns: the monthly enrollment premiums, the applicable Benchmark Silver Plan (SLCSP) premiums, and the exact Advance Premium Tax Credit paid out on your behalf.
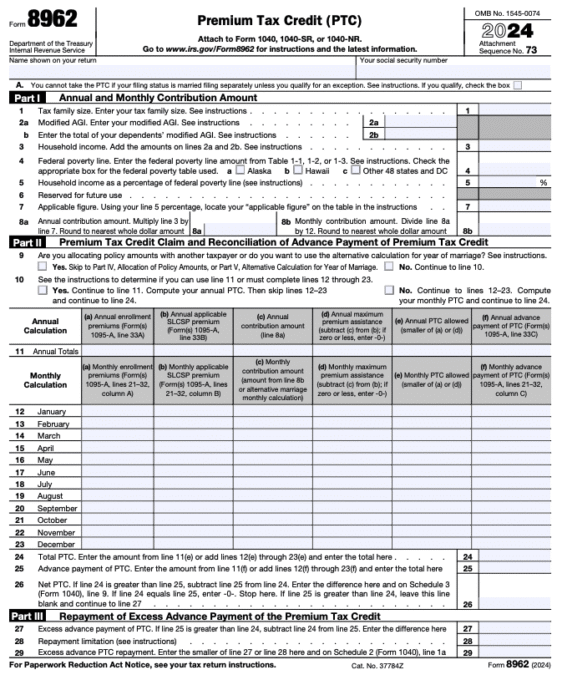
When you file your annual taxes, this data is transferred onto IRS Form 8962:
IRS Form 8962 Architecture: The Mechanics of Subsidy Recapture
| Form 8962 Section | Tax Reporting Function | Audit & Financial Impact |
|---|---|---|
| Part I: Annual & Monthly Contribution | Computes household size and actual year-end MAGI as a percentage of the Federal Poverty Level (FPL). | Determines your actual statutory percentage cap (what you legally should have paid for coverage). |
| Part II: Premium Tax Credit Claim | Reconciles allowed annual PTC against advance payments (APTC) received via Form 1095-A. | Calculates net credit owed to you OR excess payment owed back to the government. |
| Part III: Repayment of Excess APTC | Applies statutory repayment caps or transfers full liability to Form 1040, Schedule 2, Line 2. | The final dollar liability that directly wipes out your tax refund or generates a tax balance due. |
If advance credits were paid for you and Form 8962 is missing, an e-filed return may be rejected, or the IRS may send a letter asking for the form, which can delay any refund. Not filing and reconciling can also affect eligibility for advance credits in later years.
3. Statutory Repayment Caps: Are You Financially Protected?
Recognizing that predicting income 14 months in advance is challenging for self-employed individuals and hourly workers, Congress codified statutory repayment limits under 26 U.S.C. Section 36B(f)(2)(B).
For many past tax years, households whose final income stayed under 400% of the Federal Poverty Level had their repayment limited to a set dollar amount. The limit was lower for lower incomes, differed for single filers and other filing statuses, and was adjusted each year. Households at or above 400% FPL had no limit and repaid the full excess.
Important: These limits are set by law and have changed. Federal legislation enacted in 2025 changed the repayment limitation for tax years beginning after 2025, so do not assume a cap from an earlier year still applies. The table of repayment limits, if any, for the year you are filing is printed in the IRS Instructions for Form 8962 for that year. Check the current instructions at IRS.gov or ask a tax professional before relying on a cap.
4. What About Cost-Sharing Reductions (CSR)? The Good News
If you underestimated your income, enrolled in an enhanced Silver plan, and enjoyed a $0 deductible and $5 specialist copays all year thanks to Cost-Sharing Reductions (CSR), you might fear that the IRS will demand repayment of medical costs paid by the insurer.
Under federal law, Cost-Sharing Reductions are never clawed back. Under 45 C.F.R. Section 156.410, CSR subsidies are reconciled directly between the insurance carrier and the federal government. Even if your income turns out higher, the reduced deductibles and copayments you used during the plan year are not reconciled on your tax return. Only the Premium Tax Credit (APTC) is subject to tax reconciliation.
5. Three Steps to Review Before You File
If tax preparation software shows that you owe an excess premium tax credit repayment, review these options before finalizing your return. Whether each one applies depends on your situation and the eligibility rules for that account or election:
Step 1: Deploy Retroactive Above-the-Line Deductions
Because the ACA calculates subsidies based on Modified Adjusted Gross Income (MAGI), reducing your Adjusted Gross Income (Line 11 on Form 1040) directly reduces your Form 8962 repayment liability:
- Traditional IRA Contribution: Make a deductible traditional IRA contribution up to the annual statutory limit before the April tax filing deadline. Every dollar contributed reduces your MAGI dollar-for-dollar, which can increase the credit you are allowed and shrink the excess. Deductibility depends on your income and whether you have a workplace retirement plan.
- Health Savings Account (HSA) Deposit: If you were enrolled in an HSA-qualified high-deductible health plan, fund your HSA prior to the tax filing deadline to shield thousands from your MAGI.
- Solo 401(k) / SEP-IRA: If self-employed, contributions to an eligible retirement plan may reduce your MAGI. Deadlines and limits differ by plan type, so confirm what can still be contributed for the tax year.
Step 2: Check for Mid-Year Reporting Adjustments
If your income surged during the latter half of the year, make sure you update your marketplace profile immediately in future years. Under 45 C.F.R. Section 155.330, enrollees are legally required to report income shifts within 30 days. Updating your account mid-year stops the excess subsidy accrual, protecting you from year-end compounding debt.
Step 3: Review Alternative Calculation for Year of Marriage
If you got married during the tax year and your joint household income triggered an excess subsidy clawback, you may elect the Alternative Calculation for Year of Marriage on Form 8962 (Part V). This complex IRS rule allows you to recalculate your pre-marriage months using single-filer poverty benchmarks, which can reduce the repayment in some cases.
6. How to Avoid the Problem Next Year
- Estimate conservatively. If your income is irregular, base your estimate on a realistic full-year figure, not your slowest months.
- Report changes when they happen. Log in to HealthCare.gov or your state marketplace and update your income after a raise, a new job, or a large contract. Your advance credit is adjusted for the remaining months.
- Consider taking less in advance. The Marketplace lets you apply only part of the credit to your monthly premium. Any credit you did not use in advance is claimed on your tax return if you qualify.
- Check in mid-year. Compare year-to-date income with your estimate around June and again in the fall.
- Keep Form 1095-A. You need it to complete Form 8962. If it looks wrong, contact the Marketplace for a corrected form before filing.
Related guides: how income thresholds affect ACA subsidies, how seasonal income spikes affect reconciliation, and ways freelancers can manage adjusted gross income.
7. Questions to Ask a Tax Preparer
- Based on my final MAGI, what premium tax credit was I actually allowed, and how much is excess?
- Does any repayment limitation apply for the tax year I am filing?
- Can I still make a deductible IRA or HSA contribution for this tax year, and how would it change the result?
- Does my household size or filing status on the return match what I told the Marketplace?
- If I cannot pay the balance at once, what IRS payment options are available?
Frequently Asked Questions
Is underestimating income illegal?
An honest estimate that turns out low is not a violation; the system expects estimates to be reconciled. Knowingly giving false information on a Marketplace application is a different matter and can carry penalties.
Is Form 8962 an audit?
No. It is a standard tax form that compares the credit you received in advance with the credit your final income supports. Everyone who received advance credits files it.
What if my income ended up lower than I estimated?
You may be allowed a larger credit than you received, and the difference is claimed on your return. If income falls below the minimum for Marketplace credits, other rules can apply; ask a tax professional.
What if I cannot afford to repay the excess?
The excess becomes part of your tax balance. The IRS offers payment plans for taxpayers who cannot pay in full; see IRS.gov for current options.
The Bottom Line
An Advance Premium Tax Credit is a vital tool for healthcare affordability, but underestimating your earnings turns that benefit into an unexpected tax assessment. The Form 8962 reconciliation is required whenever advance credits were paid. By monitoring your income during the year, understanding statutory repayment limits, and using above-the-line retirement deductions to manage your MAGI, you can protect your tax refund and navigate marketplace subsidies without costly surprises.