
The Core Legal Remedy
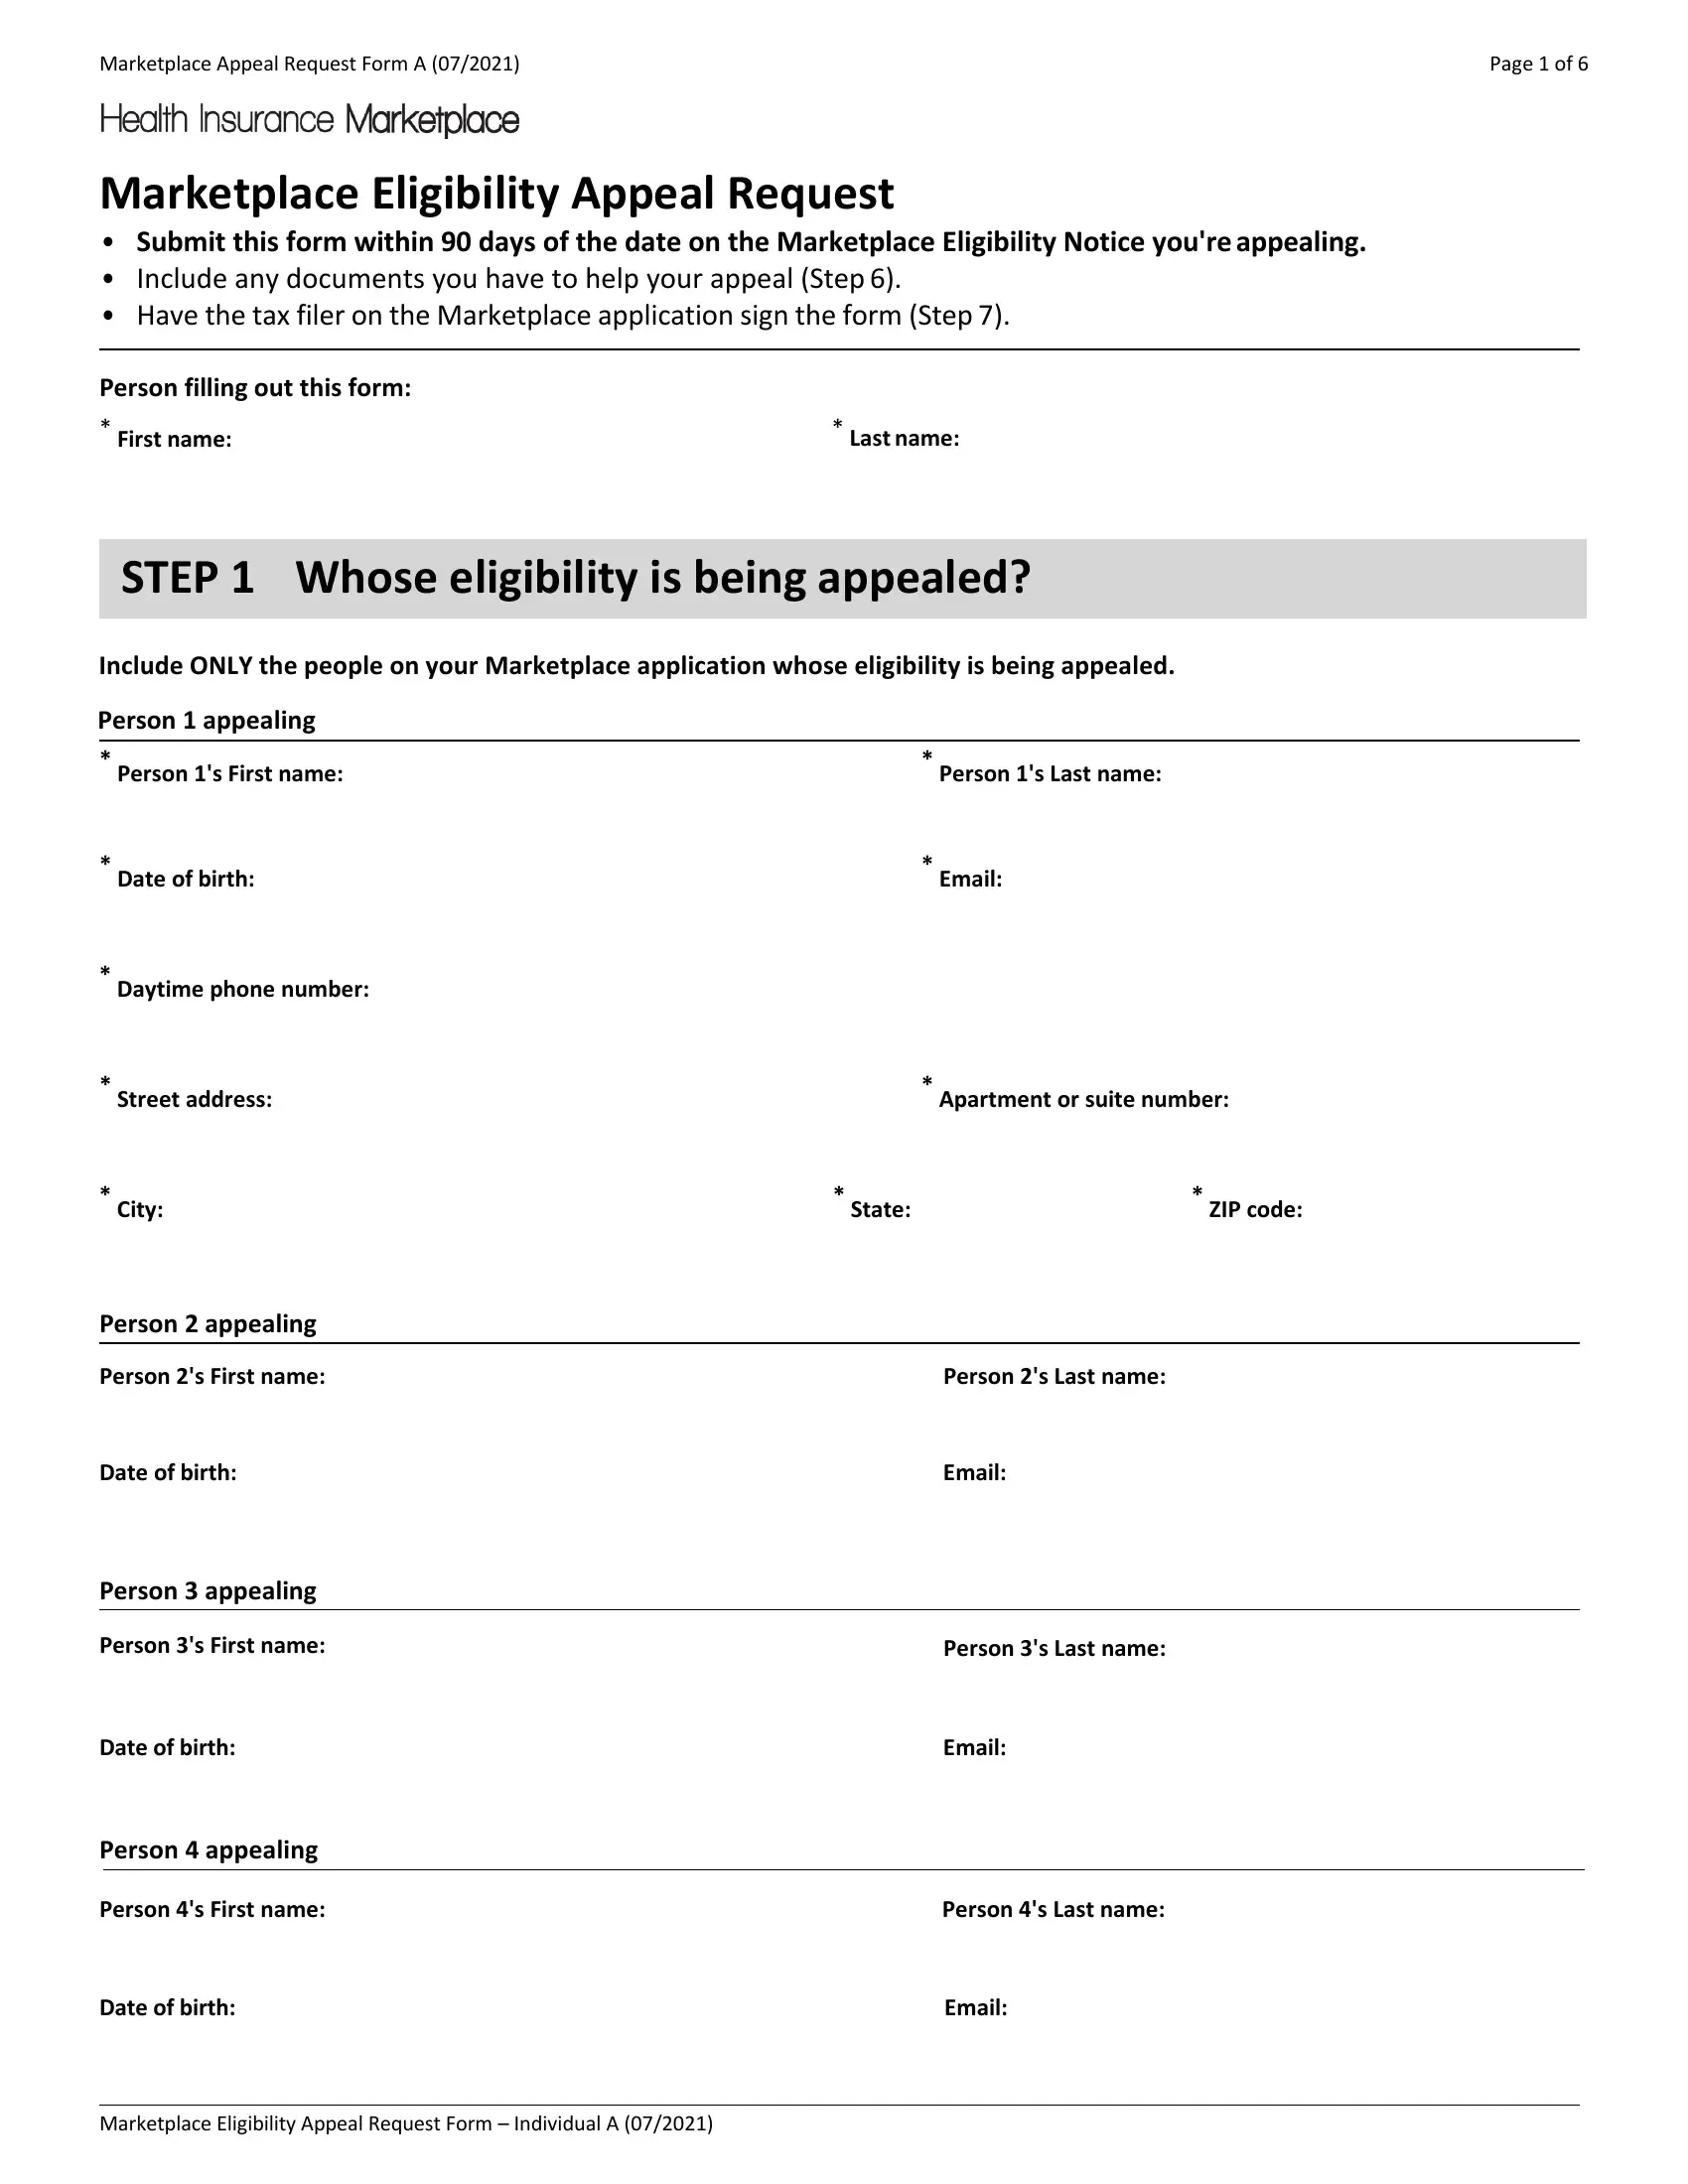
An incorrect Eligibility Determination Notice from HealthCare.gov is not final. Under 45 C.F.R. § 155.520, you generally have 90 days from the date on your notice (state-based marketplaces may set their own procedures, so check the notice itself) to file an administrative appeal with the Health Insurance Marketplace Appeals Entity. Submitting a formal appeal allows you to dispute incorrect household size counts, outdated IRS transcripts, and employer coverage misclassifications before an independent hearing officer.
You submit your annual marketplace application, expecting the portal to calculate a standard $450 monthly Advance Premium Tax Credit (APTC) and qualify your household for a low-deductible Silver Cost-Sharing Reduction (CSR) plan. Instead, the portal generates an Eligibility Determination Notice stating you qualify for $0 in financial assistance, directs you to an unsubsidized $650-a-month policy, or claims you have access to “affordable employer coverage” that actually costs half your paycheck.
Most consumers assume the computer’s word is law. Calling standard frontline marketplace telephone support often results in script-reading representatives advising you to simply re-enter your information or accept the decision. If the underlying data dispute stems from conflicting federal database matches, re-submitting the same application changes nothing.
Federal rules give marketplace applicants the right to appeal an eligibility decision. By filing an appeal, you move your case from the automated application system to a person who reviews your documents and, if needed, to a hearing officer who can correct the determination. In some cases the correction can be applied retroactively.
1. What Can Be Appealed? The Statutory Scope
You cannot appeal an insurance carrier’s medical underwriting rules or plan pricing on the exchange. However, under 45 C.F.R. § 155.505(b), the Marketplace Appeals Entity holds exclusive federal jurisdiction to overturn adverse administrative decisions regarding:
- APTC and CSR Calculations: The dollar amount of Advance Premium Tax Credits granted, or improper denial of Cost-Sharing Reductions.
- Marketplace Eligibility: Total denials of eligibility to purchase a Qualified Health Plan (QHP) through the exchange.
- Special Enrollment Period (SEP) Denials: Refusal by the exchange to grant a 60-day SEP following a qualifying life event (marriage, relocation, loss of MEC).
- Exemption Certificate Denials: Rejection of a hardship or affordability exemption required to purchase Catastrophic coverage.
- Employer-Sponsored Minimum Value / Affordability Disputes: Determinations that you have access to an eligible employer plan when the workplace policy fails the affordability percentage test.
2. The Strategic Appeal Pathway: Procedural Hierarchy
The administrative appeals architecture is structured to resolve claims through progressive levels of review:
Marketplace Adjudication Stages Under 45 C.F.R. Part 155
| Adjudication Stage | Administrative Mechanism | Typical Timeline | Consumer Rights & Protections |
|---|---|---|---|
| Stage 1: Informal Resolution | Appeals specialist reviews documentation, calls appellant, and attempts to settle error administratively. | Varies; often several weeks. | You may accept the resolution or reject it and demand a formal hearing. |
| Stage 2: Formal Evidentiary Hearing | Telephone hearing before a Federal Administrative Hearing Officer. | Varies; the appeals entity aims to decide within about 90 days of the appeal request when practicable. | Right to present witnesses, cross-examine evidence, and be represented by counsel. |
| Stage 3: Expedited Appeal | Fast-tracked review where standard timeline would jeopardize life or function. | Decided within days. | Requires physician attestation of immediate medical danger. |
| Stage 4: Federal Judicial Review | Further review, including court review, may be available after the appeal decision. The decision letter explains your options. | Post-hearing exhaustion. | Review of legal error and statutory misinterpretation. |
3. Maintaining Benefits: The Continuation of Coverage Safe Harbor
One of the most powerful provisions in federal administrative law is 45 C.F.R. § 155.525: Eligibility Pending Appeal. If you are appealing an adverse redetermination that reduced or terminated your existing subsidies mid-year, you have the right to request continuation of benefits:
In plain terms, when you appeal a redetermination and ask for it, the marketplace generally keeps your tax credit and cost-sharing reductions at the level you had before the change while the appeal is pending. Read the regulation or your notice for the exact conditions.
The Financial Caution: If you elect to maintain your subsidies during the appeal, and the hearing officer ultimately rules that the exchange was correct, you are legally responsible for reconciling those advance funds on IRS Form 8962 when filing your annual taxes, subject to statutory repayment limitations.
4. Step-by-Step Playbook: Filing a Compliant Appeal
Step 1: Locate the Eligibility Determination Notice
Pull the official PDF notice from your HealthCare.gov account. Note the Notice Date. Your 90-day clock starts on that exact calendar day. Record your Application ID and the specific reason code cited for the unfavorable calculation.
Step 2: Complete the Official CMS Appeal Request Form
Download the official “Health Insurance Marketplace Appeal Request Form” (CMS Form). You can file online through your portal, fax the paperwork, or mail the packet to the central processing facility:
Attn: Appeals
465 Industrial Blvd.
London, KY 40750-0061
Confirm the current mailing address and fax number on the appeal form or on HealthCare.gov before you send anything, and keep proof of the date you filed. If you live in a state that runs its own marketplace, use that marketplace’s appeal process instead.
Step 3: Draft an Evidentiary Brief
Do not write emotional arguments about living expenses. Frame your petition strictly in the language of federal tax and health statutes. A clear appeal statement might read like this hypothetical example (all figures are made up for illustration):
“I am appealing the Eligibility Determination dated [date]. The marketplace used an annual income of $68,000 for my one-person tax household, which appears to come from an older tax return. My projected income for this coverage year is $34,000, as shown by the attached year-to-date profit-and-loss statement, recent bank deposit records, and the letter confirming the end of my previous job. I am asking that my eligibility for premium tax credits and cost-sharing reductions be recalculated using my current projected income.”
Step 4: Request an Expedited Appeal if Clinically Necessary
If you are actively undergoing chemotherapy, scheduled for critical surgery, or reliant on daily life-sustaining medications that you cannot purchase without immediate subsidies, ask for an expedited appeal when you file. Have your treating physician provide a signed letter stating that awaiting standard appeal processing creates an immediate risk to your life or physical health.
5. What Happens When You Win? Retroactive Relief Mechanics
If the appeals officer rules in your favor, federal regulations under 45 C.F.R. § 155.545 give you two statutory options for retroactive relief:
- Prospective Adjustment: The corrected eligibility takes effect on the first day of the following month, with future subsidies recalibrated to account for previous underpayments.
- Retroactive Premium Tax Credits: The marketplace will retroactively adjust your eligibility back to the date the incorrect determination was made. You can choose to have the excess subsidy applied toward back premiums or claimed as a lump-sum refund when filing Form 8962 at tax time.
6. A Hypothetical Example From Start to Finish
The following example is hypothetical. The names, dates and dollar amounts are invented to show how the steps fit together.
Renee left a salaried job in the spring and now freelances. When she applied for marketplace coverage, the system compared her estimate with older tax data and decided she did not qualify for a premium tax credit.
- Day 1: Renee downloads her eligibility notice and writes down the notice date and application ID.
- Day 5: She gathers her separation letter, three months of bank statements and a simple profit-and-loss summary for her freelance work.
- Day 8: She files the appeal online, attaches the documents, and saves the confirmation page.
- A few weeks later: An appeals worker calls to review her documents and offers an informal resolution that uses her current income estimate.
- Outcome: Renee accepts. Her eligibility is corrected, and she chooses to have the corrected credit applied back to the start of her coverage.
If the informal resolution had not matched her records, Renee could have declined it and asked for a hearing by phone.
7. Documents That Strengthen an Appeal
The appeals entity can only work with what it can verify. Match your documents to the issue in dispute:
- Income disputes: recent pay stubs, a letter from your employer, a year-to-date profit-and-loss statement if you are self-employed, unemployment benefit letters, and Social Security benefit statements.
- Household size disputes: your most recent tax return showing who you claim, birth or adoption records, a marriage certificate or divorce decree.
- Employer coverage disputes: a written statement from your employer showing whether coverage is offered, the lowest-cost employee-only premium, and whether the plan meets minimum value. Our article on employer coverage and marketplace subsidies explains the affordability test.
- Special enrollment disputes: proof of the qualifying event and its date, such as a coverage termination letter or a lease showing a move.
- Citizenship or immigration status issues: the specific document the notice asks for, copied clearly on both sides.
8. Common Mistakes to Avoid
- Waiting until the last week. Missing the deadline can end your appeal rights unless you can show good cause.
- Appealing the wrong thing. A claim denial or a network problem goes to your insurance company, not the marketplace appeals process.
- Sending originals. Send copies and keep a full set of everything you submit.
- Ignoring mail and phone calls. If the appeals office cannot reach you, your appeal can be dismissed.
- Overstating or understating income. Use your honest best estimate. Advance credits are reconciled on your tax return, as explained in what happens if you underestimate income on HealthCare.gov.
- Going without coverage while you wait. Ask the marketplace what your enrollment options are during the appeal so you are not left uninsured.
9. Appeal Checklist
- Eligibility notice saved, with the notice date and application ID noted
- Appeal deadline marked on your calendar
- The exact decision you disagree with written in one or two sentences
- Supporting documents copied and labeled
- Request for continued benefits or an expedited appeal included, if either applies
- Proof of filing saved (confirmation page, fax receipt or certified mail slip)
- Free help contacted if you need it. See navigators vs. insurance brokers for who can assist.
Frequently Asked Questions
Does it cost anything to file a marketplace appeal?
No. Filing an eligibility appeal is free. You may choose to pay a lawyer, but many people handle the process themselves or with free help from a navigator or legal aid office.
Can someone else handle the appeal for me?
Yes. You can name an authorized representative, such as a family member, navigator or attorney, to act for you. The appeal form explains how to do this.
What if I miss the deadline?
Late appeals may be dismissed. If you had a good reason for missing the deadline, explain it in writing and ask whether the appeal can still be accepted. You can also update your application if your circumstances have changed.
Is a marketplace appeal the same as appealing a denied claim?
No. Marketplace appeals cover eligibility decisions such as tax credits, cost-sharing reductions and enrollment periods. A denied medical claim is appealed to your health plan, followed by external review.
I live in a state with its own marketplace. Does this process apply?
The basic rights are similar, but state-based marketplaces run their own appeals offices with their own forms and addresses. Follow the instructions on your notice. Our overview of state-based marketplaces and HealthCare.gov explains the difference.
The Bottom Line
The Affordable Care Act’s automated systems process millions of applications, and database errors are common. If your eligibility notice denies or reduces the assistance you qualify for under federal law, you do not have to accept the initial result. By tracking your 90-day deadline, submitting the official CMS Appeal Request Form with verifiable financial proof, and citing governing statutory regulations, you can overturn improper decisions and restore your health coverage benefits.